Condo & High-Rise Water Damage in Georgina
Lakeside properties around Georgina deal with groundwater and seasonal flooding as much as burst pipes.
Keswick and Sutton, plus a large stock of seasonal and converted cottage properties along Lake Simcoe.
High water table, spring flooding, and burst pipes in seasonal properties left unheated over winter.
Condo water losses are rarely contained to one unit. Water finds the floor assembly and appears in the units below, which means several owners, a corporation, a property manager and more than one insurer.
Covered by insurance? We bill your insurer directly, so in most cases you pay only your deductible.
Where we work in Georgina
We cover the whole of Georgina, including Keswick, Sutton, Jacksons Point, Pefferlaw and every neighbourhood in between. Postal areas L4P, L0E.
Full neighbourhood list (6)
What we attend in condos
- Water coming through a ceiling from the unit above
- Burst in-suite supply lines and failed shut-off valves
- Washing machine and dishwasher failures
- Backed-up stack or riser affecting several units
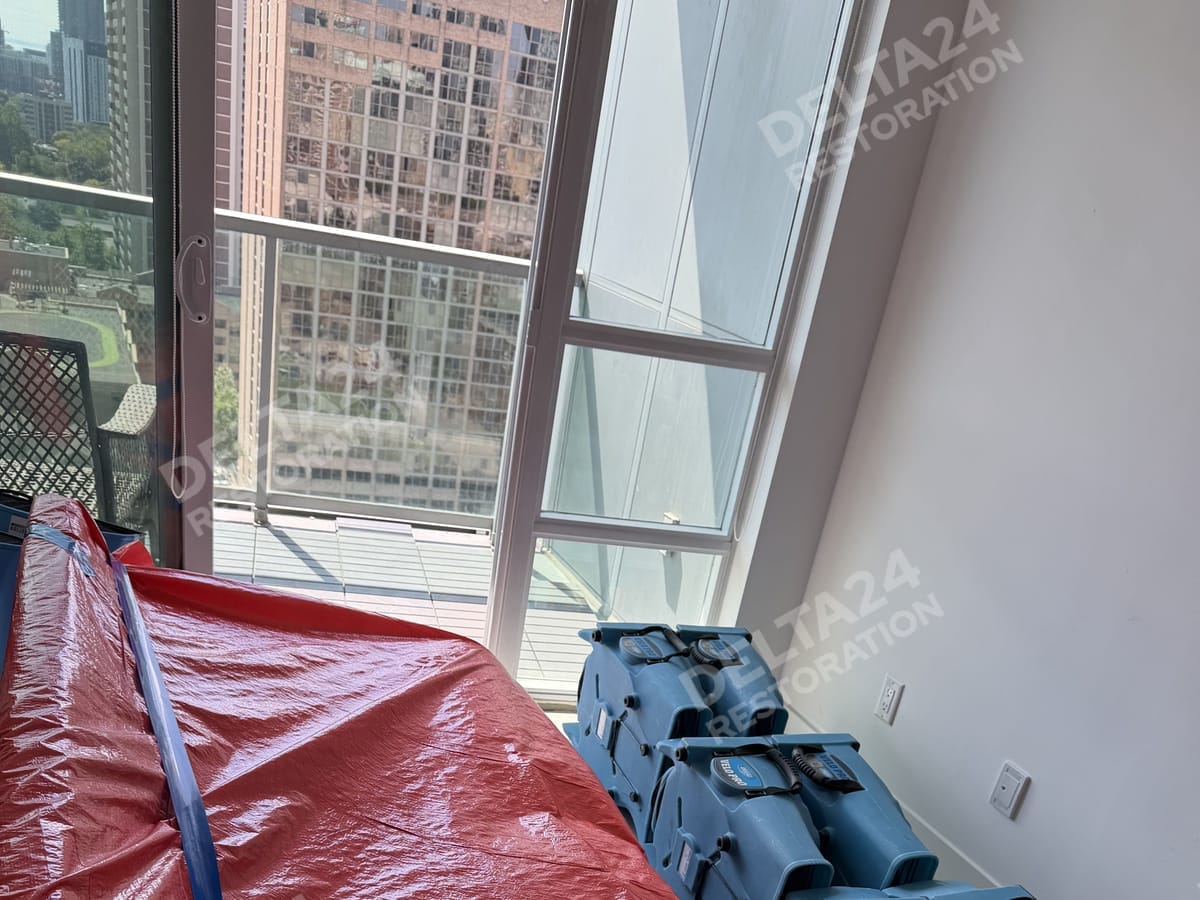
- Balcony and window leaks during storms
- Failed hot water tanks in suite
- Sprinkler discharge
What the job includes
- Attendance any hour, coordinated with building security and management
- Protection of common elements including elevators and corridors
- Moisture mapping across affected units and the floor assembly
- Extraction and drying in every affected unit
- Cavity drying inside ceiling and floor assemblies
- Separate documentation per unit for each owner and insurer
- Liaison with the property manager and the corporation
- Repairs and reinstatement of finishes
Who we do this for
- Unit owners and residents
- Condo corporations and boards
- Property managers
- Renters and landlords
- Building insurers and adjusters
When to call us in Georgina
As soon as it is noticed, and notify the property manager at the same time. In a stacked building, delay is what turns a single unit loss into four.
What condo & high-rise water damage in Georgina costs you
We bill your insurance company directly. On most covered losses that is the only amount you pay us.
Water damage is the most common home insurance claim in Ontario, and the great majority of the work we do is paid by an insurer rather than by the property owner. We document every loss from the first hour with moisture readings, photographs and a written scope, which is the evidence an adjuster needs to approve the work without argument or delay.
We work with all major Canadian insurers and handle the claim from start to finish, including the adjuster's questions. If you are not insured, or the loss falls outside your policy, we will give you a clear written quote before any work begins and we will tell you honestly what can be dried and saved rather than replaced. Keeping material in place is what keeps the cost down, and it is the first thing we look at.
There is no charge for attending to assess an emergency, and no obligation once we have. What your policy covers →
Who turns up in Georgina
Delta24 Restoration is a professional restoration contractor serving Toronto and the Greater Toronto Area. Our technicians are certified by the IICRC, the industry standards body for the restoration trade, in Water Damage Restoration (WRT) and Applied Structural Drying (ASD). We are WSIB cleared and carry full commercial general liability insurance. Certificate numbers and a current clearance certificate are provided on request, and property managers and adjusters routinely ask for both before we attend.
We work to the IICRC S500 standard for water damage restoration and the S520 standard for mould remediation. Every job is documented with daily moisture readings, photographs and a written scope, which is why adjusters approve our work without delay.
Asbestos work is carried out to Ontario Regulation 278/05, which sets out the procedures for Type 1, Type 2 and Type 3 operations. Mould work finishes with written post-remediation verification, which is the document a buyer, a lender or an insurer will ask to see.
- IICRC WRT certified technicians
- IICRC ASD certified drying
- WSIB cleared, certificate on request
- Commercial general liability insurance
- Asbestos work to O. Reg. 278/05
- Direct billing with all major Canadian insurers
- Years of insurance claim experience with every major insurer
- Written post-remediation verification on mould work
- Free assessment, no obligation
How the insurance side works
Water damage is the most common home insurance claim in Ontario, and how the claim is handled usually matters more to your bill than the work itself. We document the loss from the first hour: moisture readings, photographs, a written scope, and a daily drying log. That is the evidence an adjuster needs to approve the work without arguing about it.
We bill your insurer directly. In most cases the only money you hand over is your deductible, which on Ontario policies commonly sits between $500 and $2,500.
Which losses are covered depends entirely on where the water came from. A burst pipe or a failed appliance is normally covered under a standard policy. Water coming up through a floor drain is sewer backup, which is almost always a separate endorsement you have to have purchased. Water entering from outside during heavy rain is overland flood, which is another endorsement again. A single storm can produce all three at once, which is why adjusters care so much about the source.
Full guide: is a flooded basement covered by insurance? →
How the claim works, and what your insurer covers →
Common questions
My cottage flooded while it was closed up. What now?
Water that has run unattended for days or weeks is a different job from a fresh burst. Expect more material removal and a mould assessment as part of it.
Do you attend Georgina in winter?
Yes. Frozen and burst pipes in unheated seasonal properties are one of the main reasons we go up there.
Water came from the unit above. Who is responsible?
That depends on the source, the declaration and the corporation bylaws. Our job is to document the facts and dry the building. We will not tell you who pays, but we will give every party the evidence they need.
Do I claim on my policy or the corporation policy?
Commonly both are involved: the corporation policy covers the standard unit and common elements, and your own policy covers improvements, contents and your deductible. Report it to both.
Can you work in an occupied building?
Yes. We coordinate with security and management for access, protect the common areas and keep equipment noise to agreed hours where possible.
How do you dry a ceiling without taking it all down?
Where we can, we use cavity drying, injecting dry air into the assembly rather than opening it up. That depends on the construction and the extent of saturation.